Peter Oppenheimer argues that old school monetary policy metrics are losing their predictive power in a world driven by massive fiscal spending. This piece challenges classic economic thinking by suggesting massive government deficits could actually spark localized stock rallies instead of dragging down asset prices.
Momentum, rotation and the value in growth
Goldman Sachs
Peter Oppenheimer
Research
15 Pages
Key Takeaways
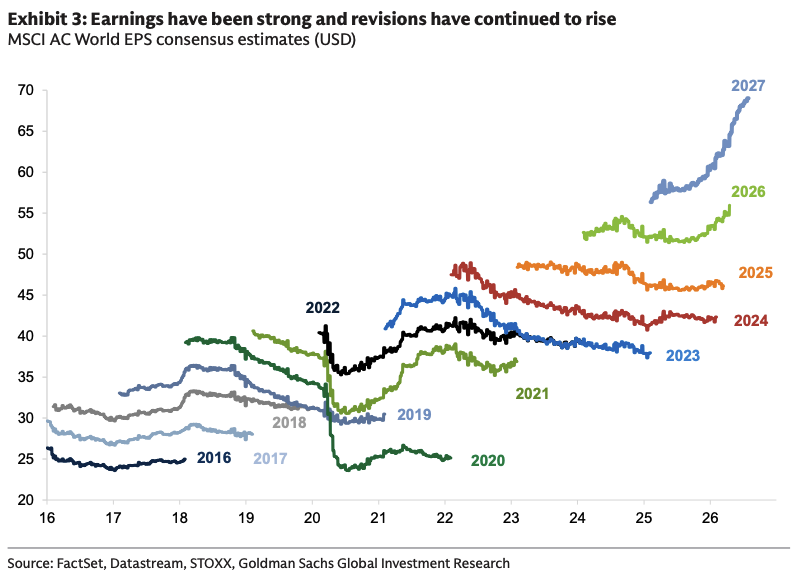
Fiscal expansion paradox: Deficit spending currently boosts corporate earnings by roughly 7% annually without crowding out private investment.
Liquidity metric divergence: Current money supply indicators lag behind specialized sovereign liquidity trackers compared to past monetary cycles.
Defensive asset repricing: Rising volatility metrics suggest sovereign debt acts more like a risk asset than a portfolio hedge.