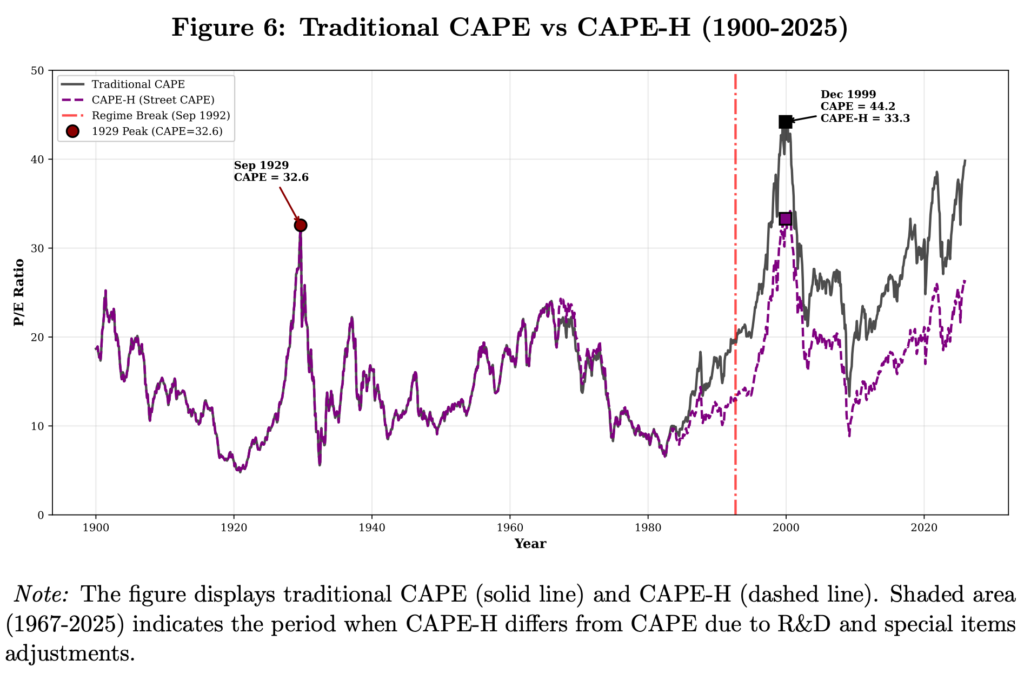
Dino Palazzo examines why the traditional CAPE ratio has overstated U.S. equity valuations since the early 1990s. The paper introduces CAPE-H, which adjusts earnings for accounting changes related to R&D and special items, restoring historical comparability and improving long-term return forecasts.
The CAPE that Cried Wolf
Dino Palazzo
Research
59 Pages
Key Takeaways
Accounting changes: GAAP earnings captured 82.3% of adjusted earnings before 1992 but only 66.6% afterward, mechanically inflating traditional CAPE valuations.
Valuation adjustment: Since 1992, traditional CAPE averaged 27.8 versus 19.3 for CAPE-H, implying a 44% valuation overstatement from accounting changes.
Better forecasts: CAPE-H improves out-of-sample price appreciation R² from −29% for traditional CAPE to +18%, strengthening long-term return predictability.