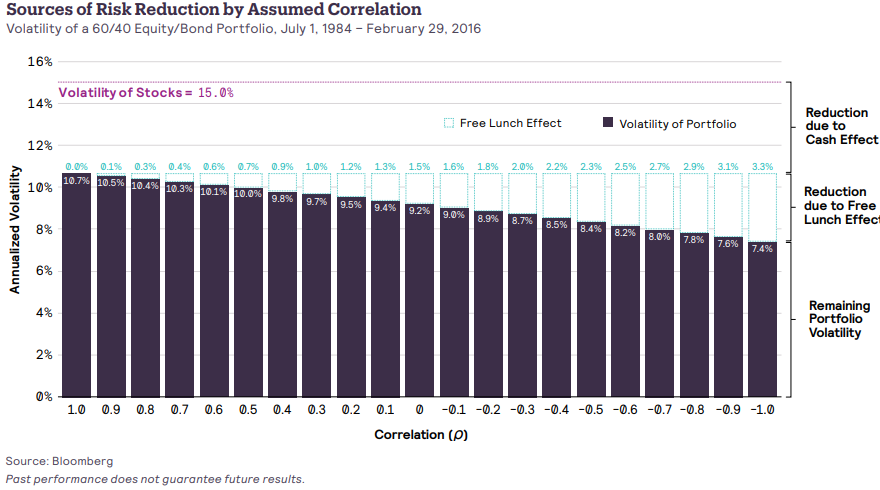
Salient Capital Advisors examines why diversification and risk reduction are not the same, arguing many balanced portfolios simply lower volatility rather than improve efficiency. The paper claims only 1.2% of the 5.7% volatility reduction in a classic 60/40 portfolio came from true diversification benefits.
The Free Lunch Effect: The Value of Decoupling Diversification and Risk
Salient
Roberto Croce
Research
12 Pages
Key Takeaways
Diversification Misunderstood: A 60/40 stock bond portfolio cut volatility from 15.3% to 9.5%, but only 1.2% came from diversification rather than lower bond risk.
Correlation Matters More: Two uncorrelated 20% volatility assets produced a 14.1% portfolio risk level and improved return per unit of risk from 0.50 to 0.71.
High Volatility Diversifiers: A diversifier with equity like volatility and 0.10 correlation contributed more portfolio diversification than a low volatility asset with perfect negative correlation.