How Not to Get Fired with Smart Beta Investing

Research Affiliates

Research

14 Pages

Research Affiliates examines how institutional incentives push investors toward “safe” smart beta allocations that may protect careers more than portfolios. The paper argues three year evaluation periods encourage benchmark hugging even when stronger factor strategies can produce materially better long run outcomes for principals.

Key Takeaways

Career Risk Distortion: Traditional Style Box allocations lowered firing risk near 0% despite producing 100–130 bps less value add than robust factor allocations over 1967–2016.
Long Horizon Advantage: A $100 investment in the Value/Momentum strategy grew to $614 in real terms versus $517 for the Traditional Style Box allocation from 1967–2016.
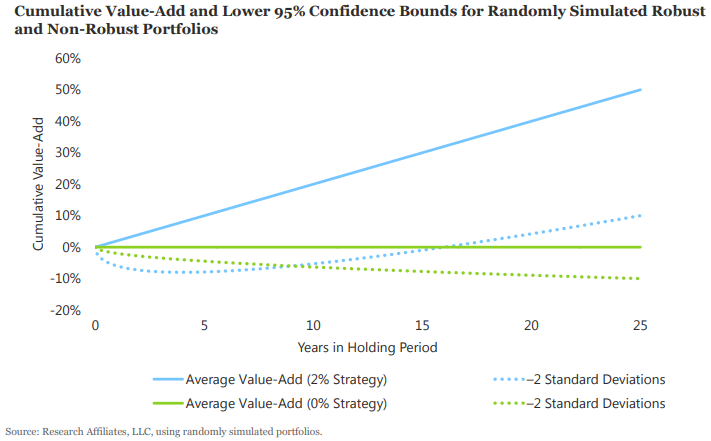
Short Term Pressure: Nearly 38% of simulated portfolios underperformed after one year, while only 25% underperformed after three years, highlighting how short reviews can punish robust strategies.

Join our newsletter to have all of this content + Exclusive Newsletter Bonus Content delivered to your inbox every week

Scroll to Top
