Relative Strength Strategies for Investing

Cambria Investments

Research

22 Pages

Cambria Investment Management explains how simple relative strength, or momentum, strategies can improve risk adjusted returns across equity sectors and global asset classes. The paper shows these approaches outperformed buy and hold in roughly 70% of years while adding trend following helped reduce both volatility and drawdowns.

Key Takeaways

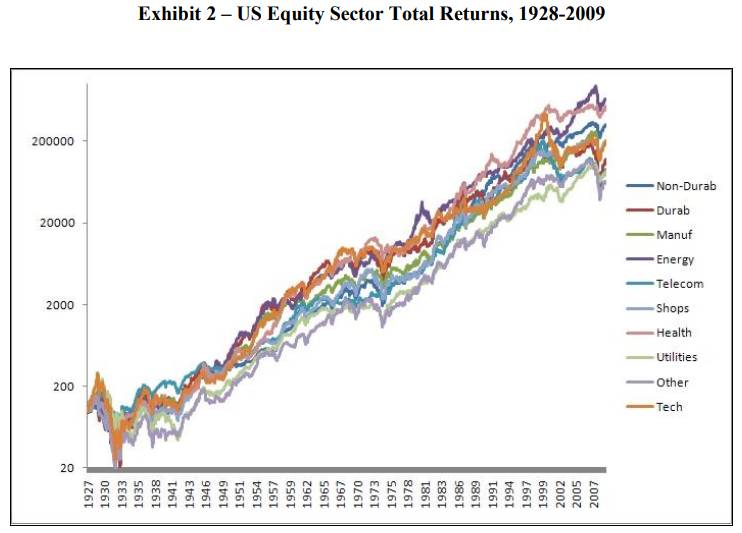
Persistent Outperformance: Relative strength portfolios outperformed buy and hold in approximately 70% of calendar years using French Fama U.S. sector data extending back to the 1920s.
Trend Following Benefit: Adding a trend following filter reduced volatility and drawdowns while maintaining the strategy's return profile across multiple market environments.
Global Applicability: The framework was tested across U.S. equity sectors and a diversified portfolio of global asset classes, with supporting evidence in both datasets.

Join our newsletter to have all of this content + Exclusive Newsletter Bonus Content delivered to your inbox every week

Scroll to Top
