buffet’s alpha

AQR

Research

45 Pages

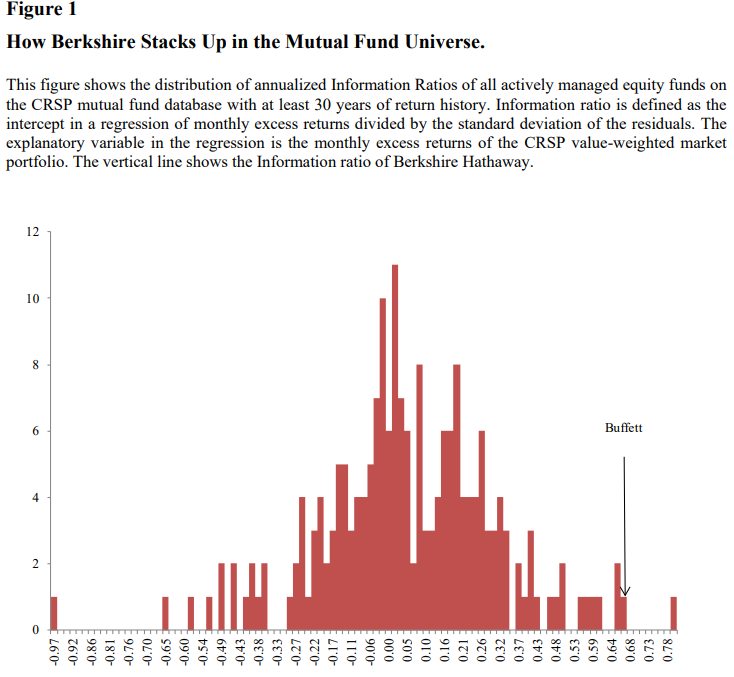
AQR Capital Management examines what really drove Warren Buffett’s long term outperformance, arguing it was not extraordinary stock picking alone but a repeatable combination of leverage, value, quality, and low risk investing. The paper also challenges the idea that Buffett’s success was luck, showing his alpha largely disappears after controlling for factor exposures.
Key Takeaways

Leverage Amplified Returns: Berkshire employed approximately 1.6 to 1 leverage, helping generate a 19.0% annual excess return versus 6.1% for the market while maintaining a 0.76 Sharpe ratio.
Quality Drove Performance: Controlling for BAB and QMJ factors reduced Berkshire’s public portfolio alpha to just 0.3%, suggesting much of Buffett’s performance reflected systematic exposure to quality and low risk stocks.
Stock Selection Dominated: Berkshire’s public equity portfolio achieved a 0.69 Sharpe ratio versus 0.43 for private holdings, supporting the view that Buffett’s strongest edge came from selecting publicly traded companies.

Join our newsletter to have all of this content + Exclusive Newsletter Bonus Content delivered to your inbox every week

Related Content

Asset Allocation
Nov 2026
Scroll to Top
