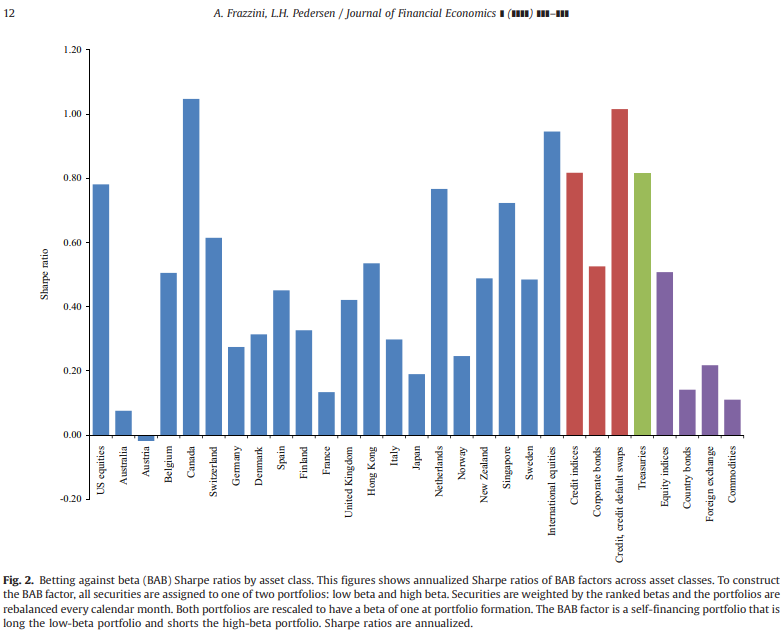
The authors examine why lower beta assets have historically delivered stronger risk adjusted returns than traditional theory suggests. Using evidence across equities, bonds, credit, and futures, the paper argues that investor leverage constraints can systematically distort pricing, creating a persistent betting against beta effect across global markets.