Familiarity Discount: The Case for Active European Value

Schroders

Research

3 Pages

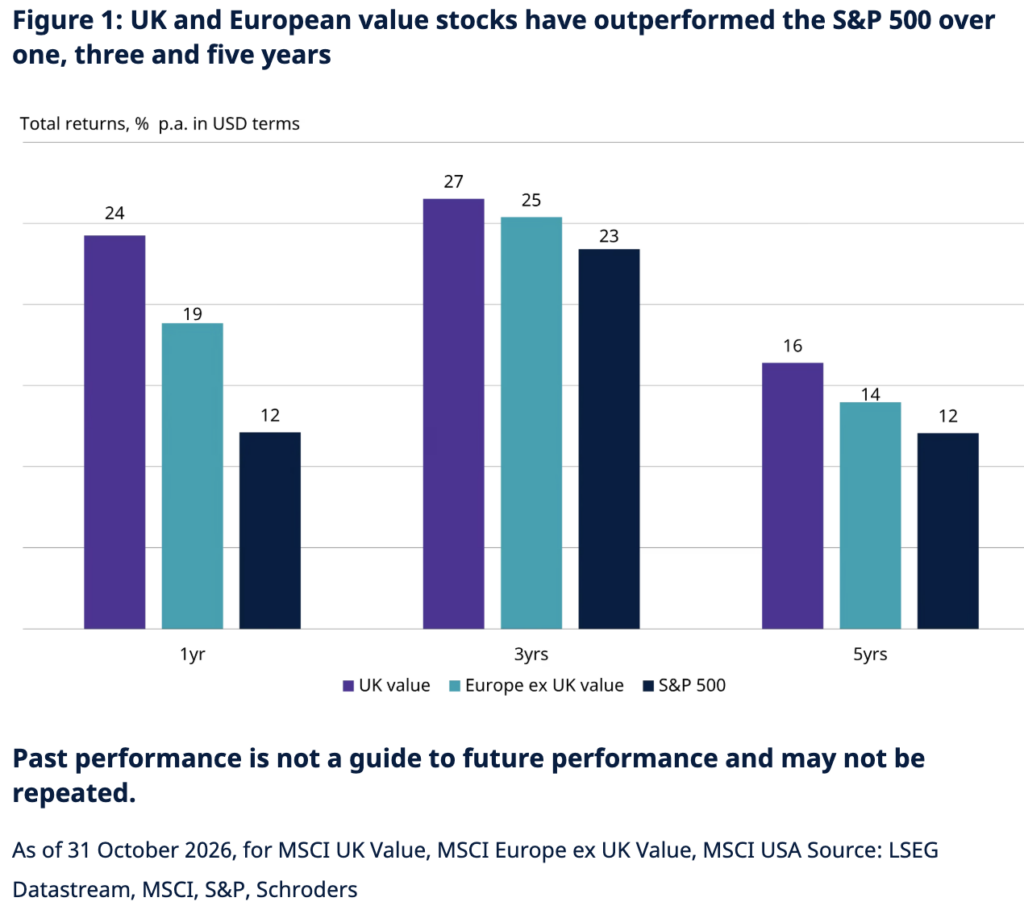
Schroders’ Andrew Lyddon argues that investors are overlooking the value opportunity in European equities, even though European value stocks have outperformed the S&P 500 over one, three and five years. He makes the case for active over passive European value, noting that passive value indices are heavily weighted to financials and hold surprisingly little of the cheapest third of the market, while the richest value today sits in small and mid-caps.

Key Takeaways

Value Beats the S&P: UK value stocks returned 24% over the past year versus 12% for the S&P 500, and European value has also led over three and five years.
Passive Value Falls Short: Only about half of the MSCI Europe Value and Enhanced Value indices sit in the cheapest third of the market by CAPE, versus about 90% for Schroders' value portfolios.
Small Caps Look Cheapest: European value stocks under €5bn offer an earnings yield about 200bps higher than those above €20bn, near the top of the normal range.

Join our newsletter to have all of this content + Exclusive Newsletter Bonus Content delivered to your inbox every week

Related Content

Market Outlooks
Nov 2026
Scroll to Top