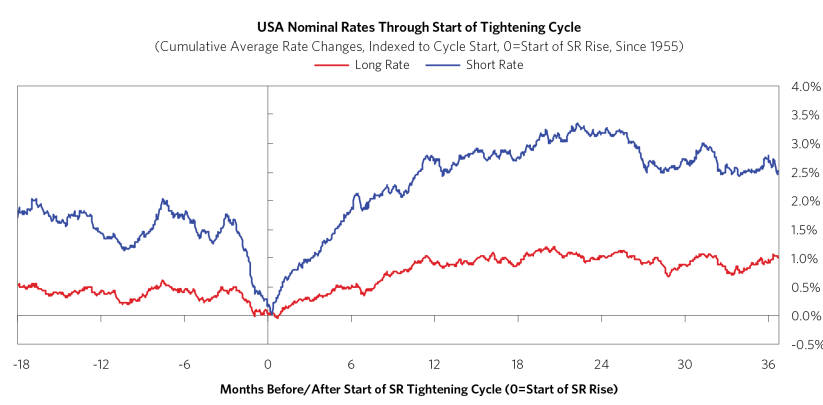
Bridgewater examines why rising inflation and nominal growth were pushing bond yields higher while central bank policy held them down. Drawing on 12 US tightening cycles since 1955, the paper argues bond markets historically anticipated short rate increases by less than a month.
The Countervailing Forces on Bond Yields and the Timing of a Rise
Bridgewater
Bob Prince
Article
1 Pages
Key Takeaways
Limited Market Foresight: Across 12 US tightening cycles since 1955, long term bond yields led short term rate increases by just 0.5 months on average.
Global Pattern Persists: Average bond yield lead times were 0.4 months in Europe and 3.0 months in Japan, suggesting limited advance signaling across major markets.
Wide Timing Range: US bond yields ranged from leading short rates by 10 months to lagging them by 15 months across historical tightening cy