Two Centuries of Price-Return Momentum

Financial Analysts Journal

Research

25 Pages

Financial Analysts Journal examines whether momentum investing persisted across 212 years of US market history using newly assembled stock data from 1801 onward. The paper argues momentum crashes often coincide with regime shifts, while long term excess returns remained surprisingly resilient across multiple centuries of market history.

Key Takeaways

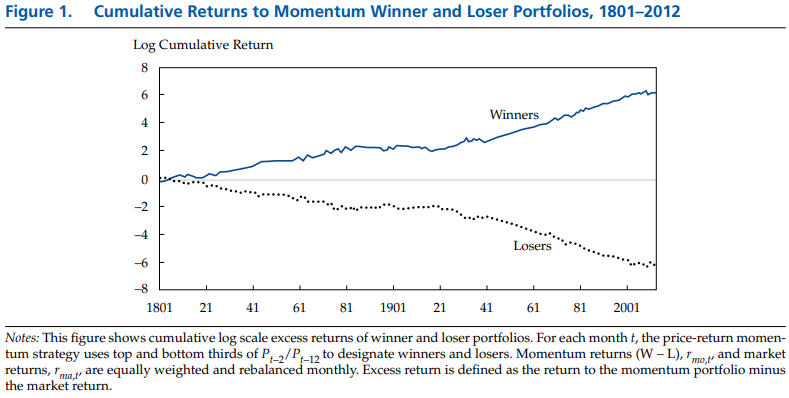
Momentum Persistence Confirmed: The winner minus loser portfolio generated 0.40% average monthly excess returns from 1801–2012 across 2,543 months of data.
Decade Long Drawdowns: Momentum experienced seven separate 10 year negative periods, including annualized losses of -2.1% during both 1900 and 2002–2012 periods.
Turnover Remains High: Pre-1927 momentum portfolios averaged 27.6% monthly turnover, suggesting implementation costs likely reduced realized returns despite strong gross performance.

Join our newsletter to have all of this content + Exclusive Newsletter Bonus Content delivered to your inbox every week

Related Content

Scroll to Top