The Cross-Section of Stock Returns before CRSP

Research

107 Pages

Guido Baltussen, Bart van Vliet and Pim van Vliet test well known equity factors out of sample using a new database of U.S. stocks from the six decades before CRSP. Value, momentum, low risk and seasonality premiums prove large and persistent in that era, while beta shows a flat relation to returns and size and reversal effects look weak.

Key Takeaways

A New Dataset: The authors build a database of 3,269 U.S. stocks from 1866 to 1926, extending cross sectional stock data to 159 years.
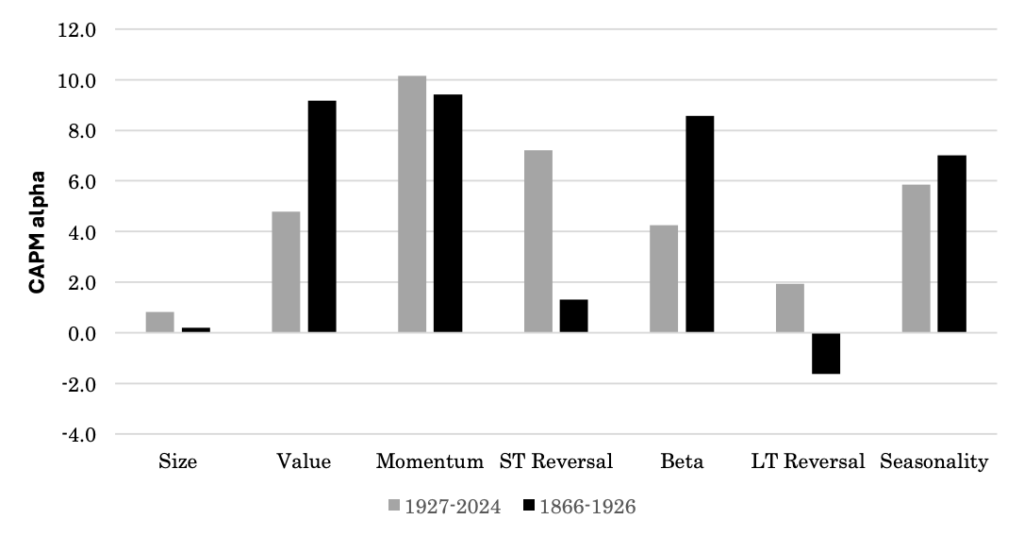
Momentum Holds Up: Momentum earned a CAPM alpha of roughly 9% a year before 1926, close to the roughly 10% it earned from 1927 to 2024.
Value Was Stronger: Value's CAPM alpha was about 9% a year from 1866 to 1926, nearly double the roughly 5% seen from 1927 to 2024.

Join our newsletter to have all of this content + Exclusive Newsletter Bonus Content delivered to your inbox every week

Related Content

Portfolio Management
Oct 2026
Asset Allocation
Oct 2026
Scroll to Top