Multi-Asset Insights: Building resilience across regimes and regions

HSBC Asset Management

Research

20 Pages

HSBC Asset Management argues that diversification has become more regime dependent as stock bond hedges, currencies, commodities and EM exposures behave differently across shocks. It pushes investors away from static 60/40 thinking toward dynamic hedging and selective EM allocations tied to AI, metals and external balance resilience.

Key Takeaways

Hedges Need Context: Average pairwise multi-asset correlation rose from near 0.10 in 2002 to roughly 0.40 by 2025, weakening simple diversification assumptions.
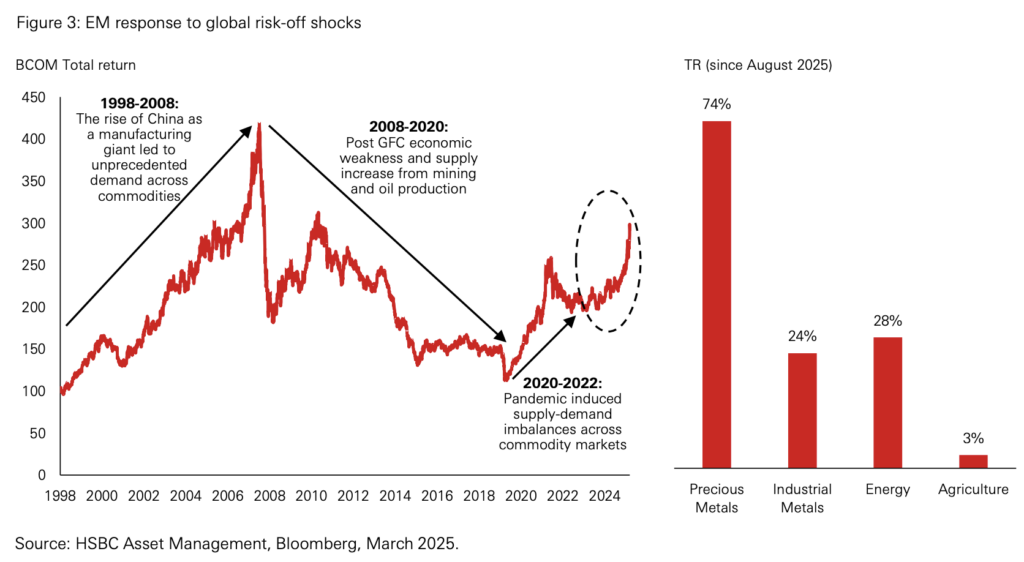
Metals Drive EM: Since August 2025, precious metals returned 74% and industrial metals returned 24%, highlighting commodities as a structural EM theme.
Chokepoints Still Matter: Roughly 80% of China’s imported crude and 90% of Japan and South Korea’s energy imports pass through the Strait of Malacca.
SBC = stock/bond correlation

Join our newsletter to have all of this content + Exclusive Newsletter Bonus Content delivered to your inbox every week

Related Content

Asset Allocation
Nov 2026
Scroll to Top