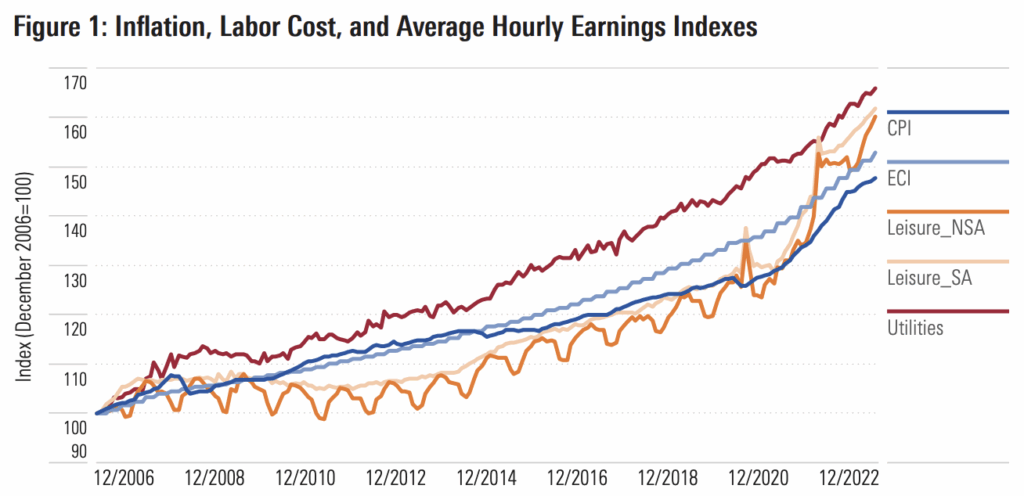
Morningstar explores how investors can improve risk-adjusted returns by aligning stock portfolios with their nontradable wealth, such as human capital and restricted stock units. Using data on 263 U.S. firms from 2013–2022, the paper shows that “total wealth optimization” reduces idiosyncratic risk far more effectively than simple company or sector exclusions.
Should Your Stock Portfolio Consider Your Career?
Morningstar
Philip Straehl, Robert ten Brincke, Carlos Gutierrez Mangas
Research
35 Pages
Key Takeaways
Human capital link: Stock-based pay now makes up 5–7% of staff expense, raising household exposure to employer-specific risk.
Optimization edge: Total wealth portfolios improved Sharpe ratios and cut idiosyncratic drawdowns by ~1.7% vs. cap-weighted benchmarks.
Exclusion limits: Company or sector exclusions delivered little benefit, often worsening risk-adjusted returns relative to index-based portfolios.