Managed Futures as Portfolio Diversifier

CXO Advisory

Research

2 Pages

This paper revisits whether managed futures improve portfolio diversification versus hedge funds and traditional stock and bond allocations. Using 2001 through 2011 data, it argues managed futures offered stronger diversification despite lower average returns, largely because of lower correlations and more favorable return characteristics.

Key Takeaways

Lower Correlation Benefits: Managed futures showed a -0.15 correlation with stocks versus 0.80 for hedge funds, highlighting substantially stronger diversification potential.
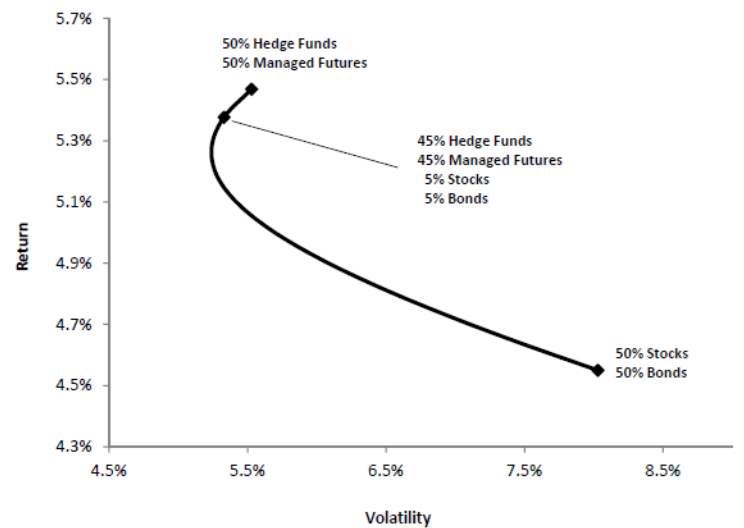
Better Portfolio Mix: Aggregate allocations of 70% to 90% in hedge funds and managed futures, including 45% to 70% in managed futures, produced the strongest overall return characteristics.
Improved Risk Profile: Across June 2001 through December 2011, increasing managed futures allocations generally reduced volatility while improving skewness and lowering kurtosis under monthly rebalancing assumptions.

Join our newsletter to have all of this content + Exclusive Newsletter Bonus Content delivered to your inbox every week

Related Content

Alternative Assets
Nov 2026
Scroll to Top