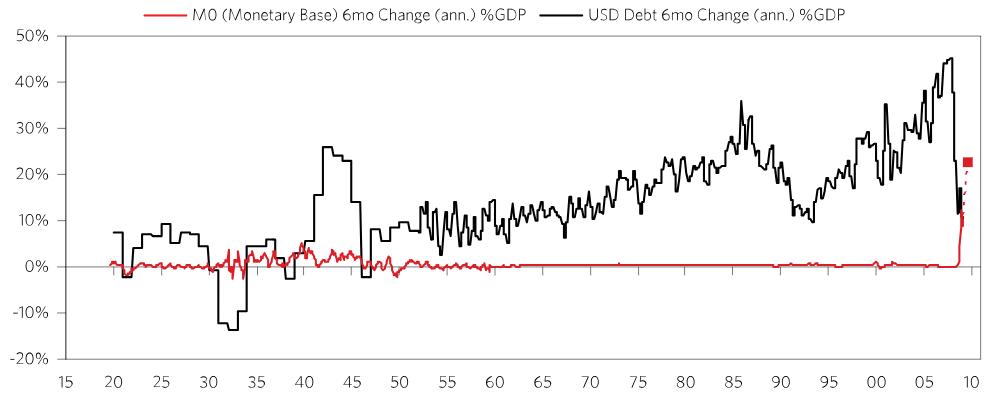
Bridgewater Associates examines how unprecedented monetary expansion could offset collapsing credit during the financial crisis, potentially making the deleveraging process less destructive. With stocks and commercial real estate already down roughly 50% since July 2007, the bigger question is whether stabilization produces real growth, inflation, or a structurally different economy.
A Modern Day D-process: A Less Traumatic Result Will Result From Increased Dosages of Money
Bridgewater
Ray Dalio, Jason Rotenberg
Article
1 Pages
Key Takeaways
Historic Monetary Response: Central banks were offsetting credit contraction with unprecedented money creation, while U.S. government purchases and guarantees had expanded to roughly 2/3 of all debt
Markets Already Repriced: Stocks and commercial real estate had fallen roughly 50% since July 2007 versus typical depression declines of 75% to 85%.
Japan Faces Pressure Japanese exports were down roughly 45%, production fell over one third, and household incomes were declining around 5% year over year.