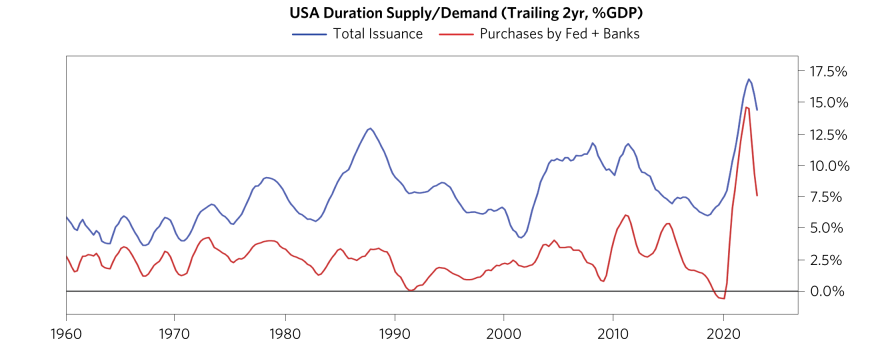
Bridgewater examines how the March 2023 bank run exposed a deeper problem for banks: rapidly rising funding costs against lower yielding assets. While emergency liquidity helped contain deposit flight, replacing cheap deposits with market rate financing could pressure profitability, lending, and monetary policy.
What We’ve Learned So Far from the Bank Run
Bridgewater
Alex Schiller, Greg Jensen
Article
1 Pages
Key Takeaways
Emergency Lending Concentrated: About 85% of Fed emergency lending, roughly $250 billion, went to just three institutions, suggesting acute stress remained relatively concentrated.
Deposits Became Expensive: Bank deposit costs reached 0.8% by Q4 2022 versus roughly 5% T bill yields, creating the widest gap in 40 years.
Funding Shift Accelerated: At least $400 billion exited vulnerable banks from March 8 to March 15, while the Fed expanded bank lending by $305 billion. Top Figures/Charts