The Age of AI Has Exposed the Structural Flaws of Cap-Weighted Benchmarks

Schroders

Research

6 Pages

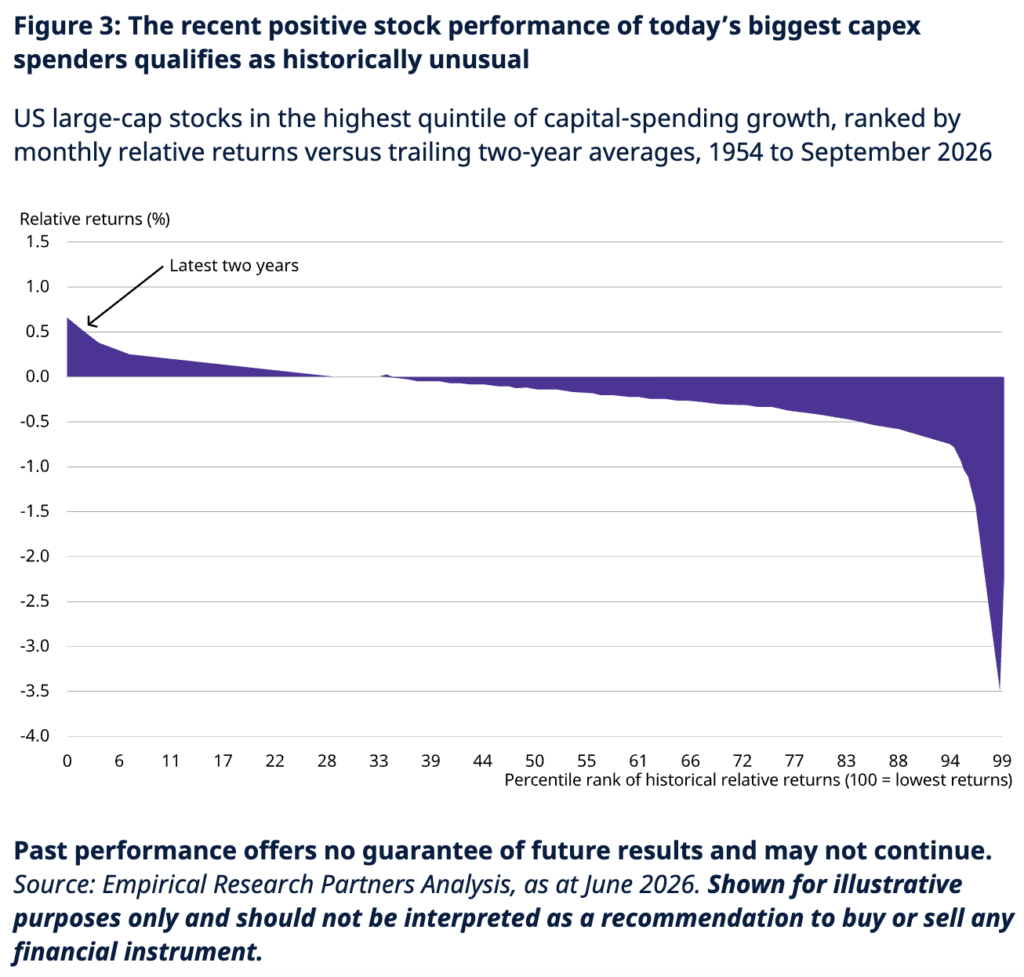
Schroders’ Frank Thormann argues that cap-weighted benchmarks have become far less neutral than they look, as a handful of megacap tech firms dominate major indices while AI capital spending reaches enormous levels. He revisits the investment anomaly, where the heaviest capex spenders have tended to lag, and makes the case for separating moat-deepening investment from a costly capital race.

Key Takeaways

Top-Heavy Benchmarks: The 10 largest companies make up almost 40% of the S&P 500, a level last seen in the mid-1960s.
Capex at Scale: Five hyperscalers account for 80% of an estimated $1 trillion in 2026 AI capex, and Schroders sees industry spending doubling to $2 trillion in 2027.
Concentration Cuts Deep: In 2022 the S&P 500's 10 largest stocks lost 37% of their combined value, versus about 20% for the index.

Join our newsletter to have all of this content + Exclusive Newsletter Bonus Content delivered to your inbox every week

Scroll to Top