Investor Psychology and Security Market Under‐ and Overreactions

Research

47 Pages

The authors develop a behavioral model explaining why markets can underreact and overreact to information. Investor overconfidence pushes prices too far on private signals, while biased self attribution can sustain momentum before eventual reversals, linking psychology to several well documented return anomalies.

Key Takeaways

Confidence Drives Mispricing: A 50,000 run simulation shows prices rising from 0.5 to 0.7366 by period 16 before gradually reversing toward fundamental value.
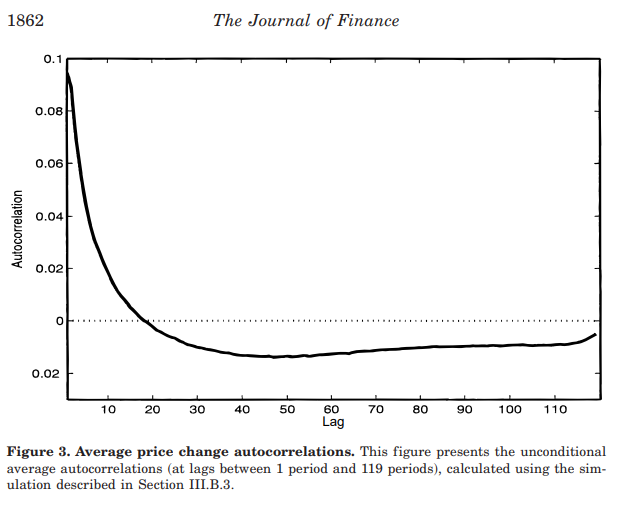
Momentum Eventually Reverses: Simulated return autocorrelations across lags from 1 to 119 periods shift from positive at short horizons to negative at longer horizons.
Culture May Matter: The authors cite 23 Japanese studies finding essentially no self enhancing attribution bias, consistent with comparatively weak momentum evidence in Japan.

Join our newsletter to have all of this content + Exclusive Newsletter Bonus Content delivered to your inbox every week

Scroll to Top