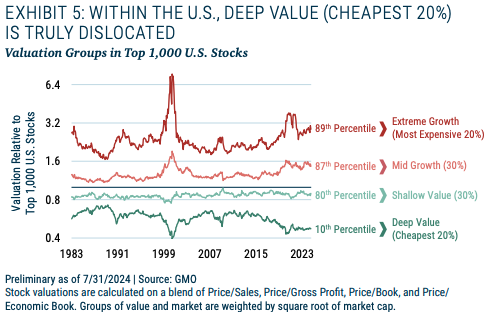
GMO argues that deep value stocks—those trading far below their fundamental worth—offer a historically attractive opportunity. By relying on internally restated financials rather than traditional value labels, GMO claims to identify higher-quality, mispriced equities.
A Rose by Any Other Name Would Smell as Sweet
GMO
Research
5 Pages
Key Takeaways
Extremely cheap cohort: Deep value stocks are in the 2nd percentile of historical valuation ex-U.S. and 10th percentile in the U.S.
Better value screens matter: GMO restates financials and focuses on forward-looking growth to avoid value traps and boost selection accuracy
Global bias favored: Value is already turning outside the U.S., where GMO sees better upside and more diversification from growth-heavy U.S. equities