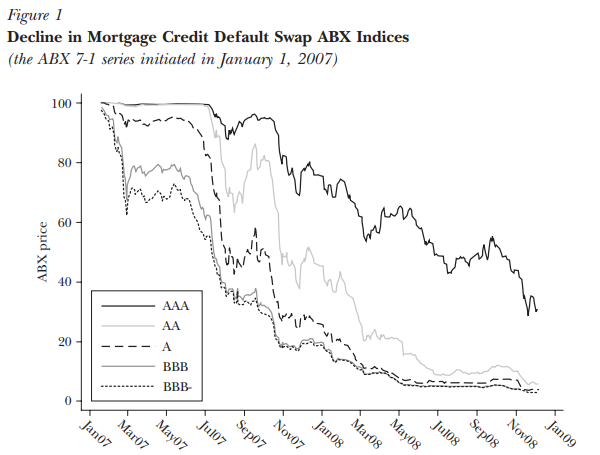
This paper explains how relatively contained mortgage losses cascaded into a broader financial crisis through securitization, fragile funding structures, and tightening liquidity. It argues that interconnected balance sheets and feedback loops magnified the initial shock, contributing to roughly $8 trillion in lost U.S. stock market wealth.
Deciphering the Liquidity and Credit Crunch 2007–2008
Markus Brunnermeier
Research
24 Pages
Key Takeaways
Losses Became Amplified: U.S. stock market wealth fell roughly $8 trillion between October 2007 and October 2008, far exceeding underlying mortgage losses.
Funding Grew Fragile: The share of investment bank assets financed through overnight repos roughly doubled from 2000 to 2007, increasing dependence on daily funding.
Credit Exposure Expanded: Outstanding credit default swaps reached an estimated $45 trillion to $62 trillion in 2007, illustrating the scale of interconnected credit exposure.