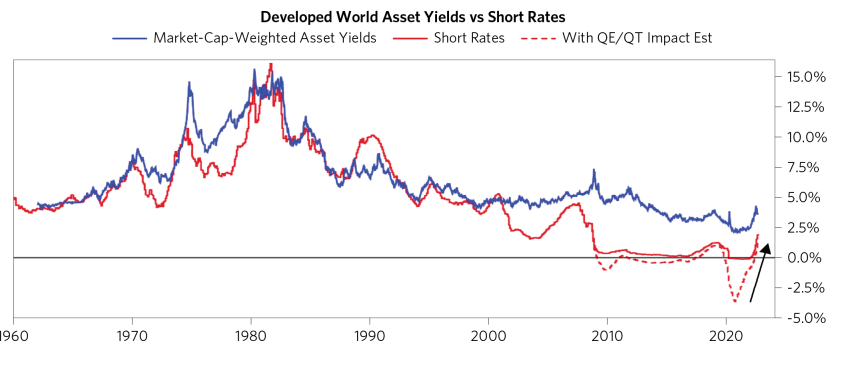
Bridgewater examines why equities may not fully reflect the economic and earnings consequences of monetary tightening. Markets had largely repriced higher rates, while earnings expectations barely moved. The paper argues that weaker growth, stubborn inflation, or further tightening could create additional pressure on equity valuations.
Equity Markets Aren’t Pricing in the Next Stage of the Tightening Cycle
Bridgewater
Aaron Goone, Bob Prince
1 Pages
Key Takeaways
Earnings Risk Remains Across 41 bear markets and 30 corrections over 100 years, earnings declines played a much larger role when equity losses exceeded 20%.
Growth Is Slowing: US real growth had already slowed to around 0%, suggesting monetary tightening was beginning to move beyond financial markets and into the economy.
Labor Pressure Persists: Wage growth was running at 6.1% annualized while the job openings rate stood at 6.6%, potentially supporting additional monetary tightening.