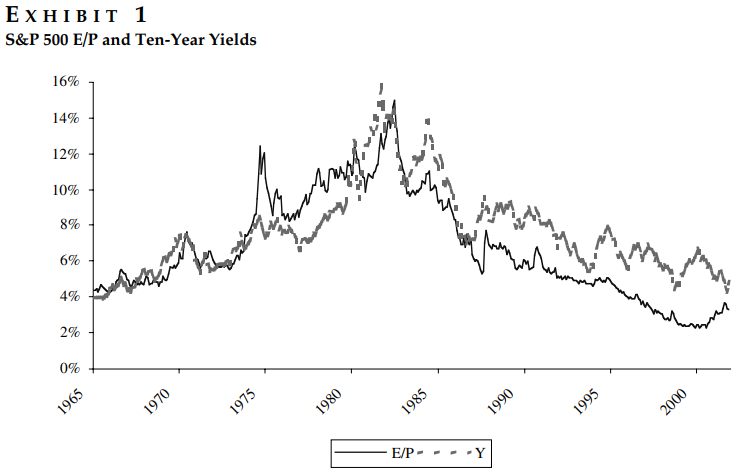
AQR challenges the popular Fed Model, arguing that comparing stock earnings yields with Treasury yields is a flawed way to value equities. Instead, the paper contends traditional valuation measures better explain long term returns, while the Fed Model mainly reflects investor behavior rather than investment merit.
Fight The Fed Model
AQR
Cliff Asness
Research
15 Pages
Key Takeaways
Traditional Valuation Wins: The traditional P/E model explained about 30.2% of subsequent 10 year real equity returns from 1881 to 2001, while the Fed Model added virtually no forecasting value.
Weak Predictive Evidence: Adding interest rates to the valuation model produced a 0.02 coefficient over 1881 to 2001, showing Treasury yields contributed almost nothing to long term return forecasts.
Risk Explains Behavior: After incorporating perceived risk, the model better explained valuation changes across 1926 to 2001, helping reconcile why stock P/Es moved with interest rates despite weak predictive power.