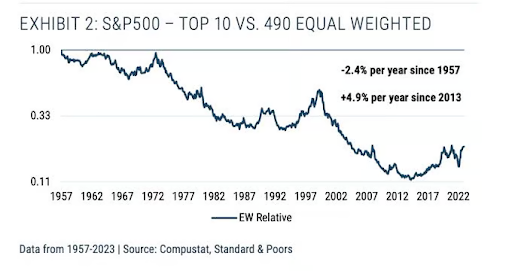
GMO’s Q1 2024 letter discusses the extreme concentration of U.S. equities, particularly the dominance of the “Magnificent Seven,” and suggests this dynamic favors active managers who deviate from cap-weighted benchmarks. The authors argue that a return to historical norms would likely benefit equal-weighted strategies and high-conviction managers.
Magnificently Concentrated: Your active managers are more competent than they look
GMO
Ben Inker, John Pease
Research
10 Pages
Key Takeaways
Unprecedented concentration: The top seven stocks make up nearly 28% of the S&P 500, an unusually high level that deviates from long-term historical patterns.
Active managers unfairly judged: Many active managers appear to underperform because mega-cap stocks dominate benchmarks, masking their relative skill.
Reversion is probable: Historical trends suggest that concentrated markets often revert, which could favor equal-weight indices and active strategies over the next decade.