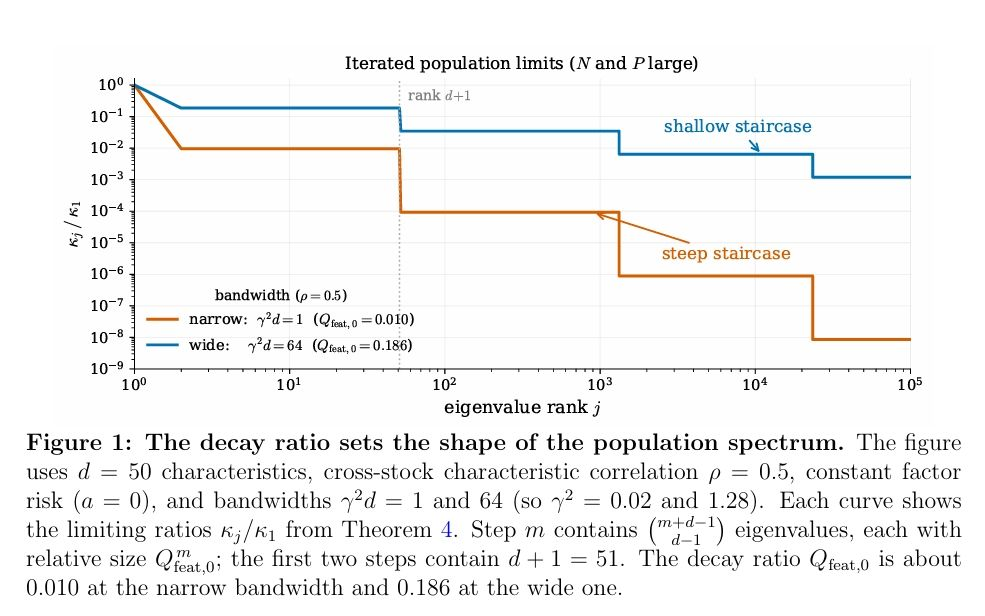
Bryan Kelly and coauthors challenge the widely held assumption that stock returns are driven by a few dominant factors followed by noise. Because risk is usually estimated by pooling returns across changing market conditions, they show a model with a few conditional factors looks like one with infinitely many. Reducing returns to a few principal components may discard priced risk.