The Quality Anomaly: The Weirdest Market Inefficiency in the World

GMO

Research

10 Pages

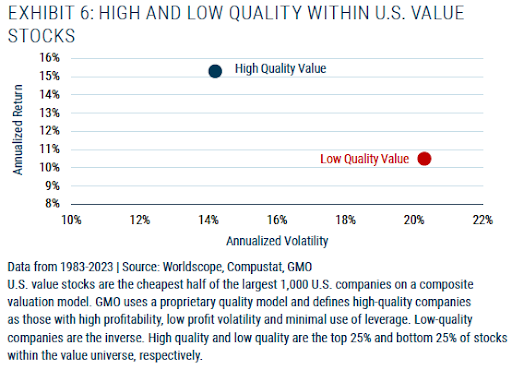
Ben Inker of GMO explores the enduring and puzzling “quality anomaly,” where higher quality equities and bonds—despite being lower risk—have historically delivered better returns. This runs counter to standard financial theory and supports a strong case for a quality tilt in both equity and high-yield bond portfolios.

Key Takeaways

Persistent Outperformance: High-quality stocks and BB-rated bonds have outperformed their lower quality counterparts despite lower risk, challenging traditional risk-return theory.
Risk Mitigation: In down markets, high-quality assets have significantly lower downside beta, offering protective characteristics during economic stress.
Broad Applicability: The quality premium exists across sectors, geographies, and asset classes—including small caps and value stocks—without demanding valuation trade-offs.

Join our newsletter to have all of this content + Exclusive Newsletter Bonus Content delivered to your inbox every week

Related Content

Portfolio Management
Oct 2026
Asset Allocation
Oct 2026
Scroll to Top