Beyond Stock Selection: A Systematic Approach to EM Country Timing

Man Group

Research

10 Pages

Man Group argues that systematic emerging market managers can add a country timing layer on top of stock selection. Mickael Nouvellon and Dawei Zhou compare a simple valuation and momentum model with a macro model built on economic logic and machine learning, using South Korea to show how macro signals shift positioning over time.

Key Takeaways

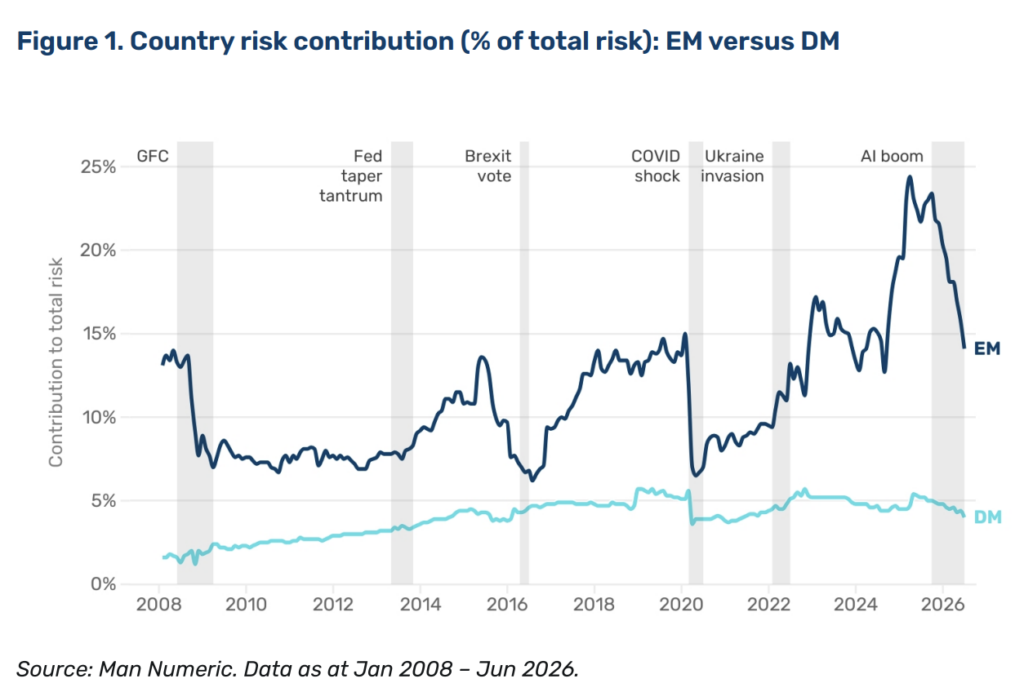
EM Country Risk Higher: Country factors explained roughly 24% of EM risk at the 2025 peak, versus about 5% for developed markets.
Macro Model Edge: Gross of costs, the macro model posted a 0.85 Sharpe ratio since 2008, versus under 0.5 for a valuation and momentum model.
Uncorrelated Alpha Source: Macro model daily returns had a 0.08 correlation with the fundamental model, and its max drawdown was 4.6% versus 8.7%.

Join our newsletter to have all of this content + Exclusive Newsletter Bonus Content delivered to your inbox every week

Scroll to Top
